The 5 P’s of Personal Finance: Purpose to Prosper
What are the 5 P’s of personal finance?
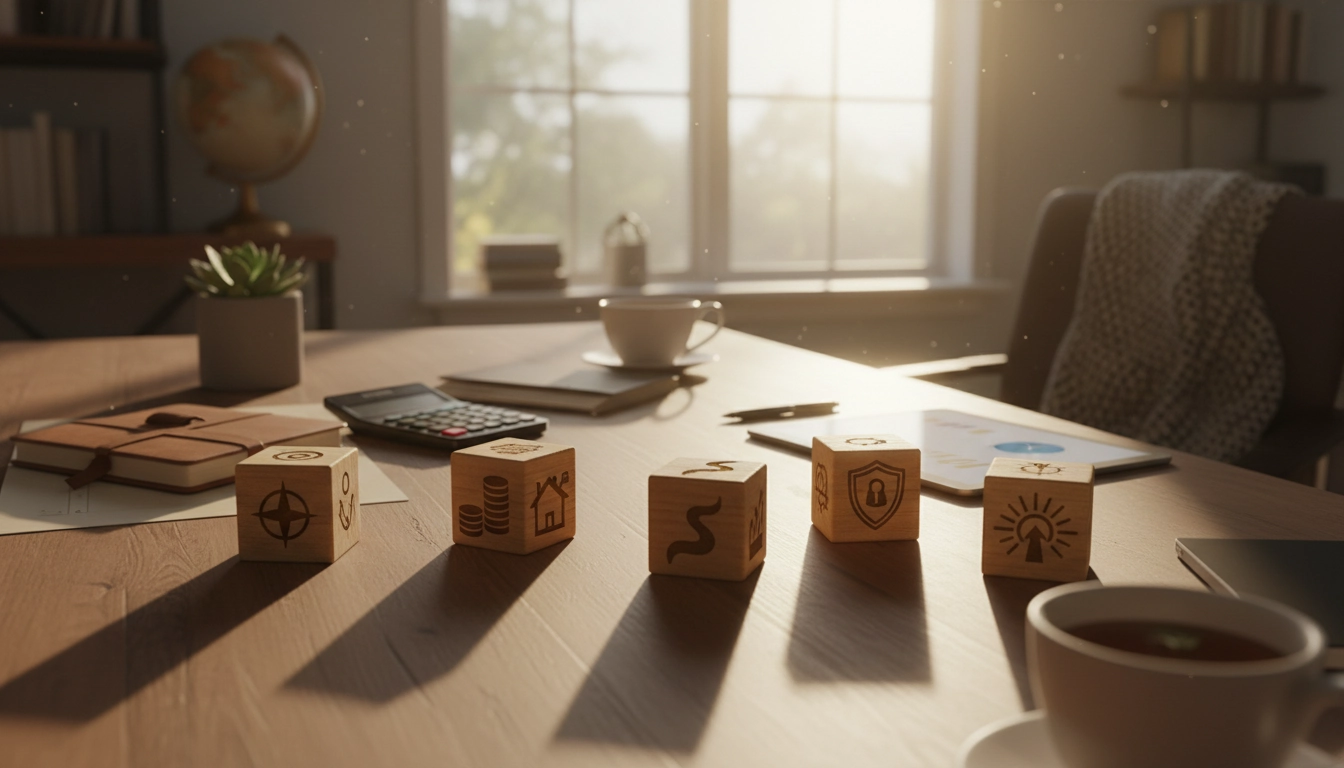
The 5 P’s of personal finance are a simple way to organize money decisions into five practical buckets: purpose, plan, pay yourself, protect, and prosper. Together, they help turn day-to-day spending into long-term progress by giving every dollar a job and every goal a timeline.
How the 5 P’s work in real life
1) Purpose
Purpose is the “why” behind your money. It could be peace of mind, buying a home, getting out of debt, starting a business, or supporting family. When purpose is clear, it’s easier to say no to expenses that don’t align with what matters most.
2) Plan
A plan turns purpose into numbers. This usually means a budget, a debt payoff strategy, and a savings target. Even a basic plan—tracking income, fixed bills, and a realistic discretionary amount—can prevent surprises and reduce stress.
3) Pay Yourself
Pay yourself means saving first, not last. Set up automatic transfers to an emergency fund and retirement accounts so progress happens even during busy months. Start small if needed; consistency matters more than perfection.
4) Protect
Protection covers the risks that can derail everything: medical costs, accidents, disability, loss of income, or identity theft. Common tools include insurance (health, auto, renters/homeowners, life where appropriate), emergency savings, and basic account security habits.
5) Prosper
Prosper is the long game—building net worth through smart investing, reducing high-interest debt, and increasing earning power. It’s also about using money intentionally once the essentials are solid, like giving, travel, or lifestyle upgrades that fit your plan.
For a deeper breakdown and examples, visit this guide to the 5 P’s of personal finance.
FAQ
What is the difference between budgeting and cash flow?
Budgeting is the plan for where money should go, while cash flow is what actually comes in and goes out over time. Strong cash flow can still feel tight without a budget, and a budget won’t work if cash flow is negative.

Leave a comment